What Evidence Do You Need for a RCV roof policy?
A roof claim documentation guide for Texas property owners from Showtime Exteriors.

For a roof claim under replacement cost value coverage, you generally need evidence of the damage, a supported repair scope, itemized costs, and—when additional payment is conditional on repairs—documentation of the work and expenses actually completed or incurred.
Start with the policy itself. Then organize photographs, inspection findings, estimates, emergency invoices, completion records, and communications.
RCV is a valuation method, not automatic approval for a new roof. Coverage still depends on the cause of loss, exclusions, endorsements, deductible, limits, and policy conditions.
The Texas Department of Insurance distinguishes replacement cost coverage, which values covered repairs at current prices, from actual cash value coverage, which accounts for depreciation. Your actual policy determines how those provisions apply to the roof. tdi.texas.gov
1. Confirm That Replacement Cost Applies to the Roof
Do not rely solely on a declarations page showing replacement cost coverage for the building.
Read the applicable policy forms and roof endorsements. Ask the insurer or agent to identify the provision governing roof loss settlement.
Collect:
- Declarations page.
- Coverage forms.
- Roof endorsements.
- Wind and hail deductible provisions.
- Relevant exclusions.
- Repair and replacement conditions.
- Reporting and document-submission requirements.
A policy may treat roof surfacing differently from other building components.
Ask for clarification in writing if the roof settlement terms are unclear. Commercial policies can contain requirements that differ from homeowners policies.
2. Document What Happened and When
Keep the event date, discovery date, and inspection date separate.
Record:
- When the weather event or other incident was reported.
- When someone first noticed a concern.
- Who made the observation.
- What was observed.
- When the contractor inspected.
- When protection or repairs occurred.
If the cause or date is uncertain, say so.
For example:
“Water entry was discovered Monday morning after a weekend storm. The roof is being evaluated to determine the source and extent.”
Avoid assigning a precise cause before the evidence supports it.
Weather information can provide context, but nearby hail or wind reports do not independently establish the damage to your roof.
3. Preserve Photographs With Clear Locations
Collect safe interior and ground-level observations. Leave roof access to qualified professionals.
Ask the roofer for a sequence that shows:
- The overall building or roof.
- The affected roof section.
- The specific condition.
- A detailed view.
Use a roof map or consistent location labels.
A close-up without a location may be difficult to connect to the estimate. Keep original image files and use separate annotated copies when arrows or labels are helpful.
Do not change the appearance of the damage or use unrelated project images.
The photographs should support the actual findings—not simply make the claim look dramatic.
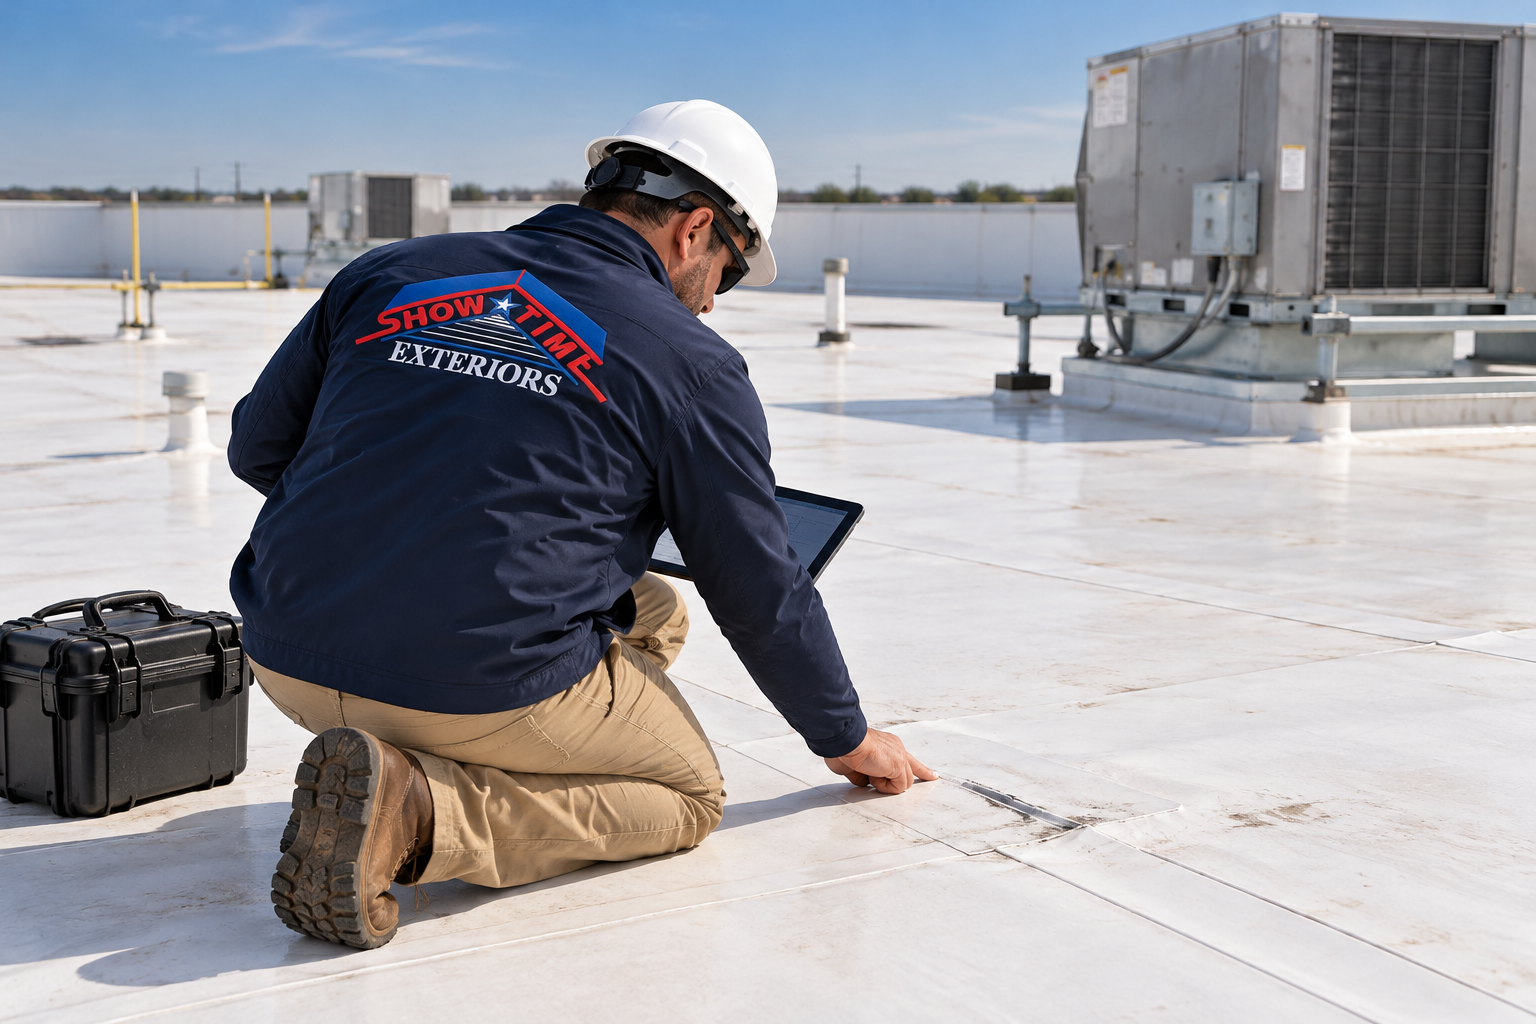
4. Obtain a Professional Inspection Report
A useful report explains the observations and the basis for the recommended work.
Request:
- Roof system identification.
- Areas inspected.
- Location-specific findings.
- Assessment of cause, where supported.
- Extent of observed damage.
- Inspection limitations.
- Additional investigation needs.
- Immediate protection recommendations.
- Repair or replacement scope.
A statement such as “storm damage—replace roof” provides limited support.
If full replacement is recommended, ask why a smaller scope would be insufficient. If repair is recommended, ask what remains outside that work.
The contractor’s physical findings and the insurer’s coverage decision are related but separate.
5. Keep the Roof’s Prior History
Prior records help explain what existed before the loss.
Collect available installation documents, product information, warranties, inspection reports, maintenance logs, repair invoices, and earlier photographs.
Identify prior leaks and distinguish their locations from current observations.
Do not omit an earlier issue. Describe its history accurately.
These records can also help establish roof age and identify the materials needed for a suitable repair.
If information is unavailable, record that limitation rather than inventing a date or product.
6. Support the Repair Scope With an Itemized Estimate
An RCV claim needs a supported construction scope.
Ask the estimate to identify:
- Measured roof areas.
- Removal and disposal.
- Replacement products.
- Insulation and underlying work.
- Flashings and associated details.
- Drainage work.
- Equipment responsibilities.
- Access requirements.
- Included fees.
- Exclusions and allowances.
Link major scope items to inspection findings or other supporting documentation.
If additional work is proposed for an applicable requirement, provide the relevant documentation and explain why it applies. Do not assume that required construction work is automatically covered without reviewing the policy.
Keep owner-selected upgrades separate from the claimed repair scope.
7. Document Emergency Protection
Urgent protection should not wait for a perfect evidence package.
Ask the contractor to photograph conditions before covering them when safe and practical. Keep the emergency authorization, scope, photographs, itemized invoice, and follow-up instructions.
Distinguish temporary protection from permanent repairs.
Report the damage promptly and ask the insurer how emergency expenses should be submitted.
Save actual receipts. An emergency expense still requires review under the policy; its submission does not guarantee reimbursement.
8. Understand the Insurer’s Estimate
Review the estimate summary and line items.
Identify:
- Replacement cost amount.
- Depreciation.
- Actual cash value amount.
- Deductible.
- Prior payments.
- Current net payment.
- Recoverable and nonrecoverable depreciation.
- Items awaiting documentation.
Ask for an explanation of any unclear deduction or condition.
Do not assume every depreciation amount is recoverable merely because the building has some replacement cost coverage.
Likewise, an initial payment is not necessarily the final settlement.
Keep each revised estimate and payment explanation in the claim file.
9. Gather Completion and Expense Evidence
When additional payment depends on repair or replacement, ask the insurer exactly what documentation it requires.
Useful records may include:
- Signed work agreement.
- Final itemized invoice.
- Completion photographs.
- Product records.
- Inspection documents.
- Approved change orders.
- Proof of payment, if requested.
- Contractor completion statement.
An estimate shows proposed cost. An invoice shows charges. A payment record shows money paid. They are different documents.
Do not assume that one replaces all the others.
For example, TWIA explains that its replacement cost claims are generally paid in stages, with recoverable depreciation following qualifying repairs or replacement under its requirements. That describes TWIA’s process—not a universal rule for every insurer. twia.org
10. Request Recoverable Depreciation Clearly
Ask the insurer for the applicable conditions and deadlines before work begins.
Confirm:
- Which depreciation is recoverable.
- What work must be completed or incurred.
- What documentation is required.
- Whether extensions are available.
- How the final payable amount is calculated.
Do not assume withheld depreciation is automatically released in full. Actual expenses, policy terms, approved scope, and limits may affect payment.
A concise submission can say:
“Attached are the final invoice and completion records for the roof work. Please review them under the policy’s replacement cost provisions and identify any additional documentation needed.”
Save the submission confirmation and response.
An Illustrative Payment Example
Assume a covered claim has:
ItemHypothetical amountApproved replacement cost$100,000Depreciation withheld$25,000Deductible$10,000Initial payment$65,000Potential additional depreciation paymentUp to $25,000
If all conditions are satisfied and the eligible amount supports full recovery, total insurer payment could be $90,000.
This is a simplified example, not a claim prediction. Lower actual costs, policy limitations, nonrecoverable depreciation, or scope changes may alter the result.
11. Document Supplements Separately
If work reveals additional conditions or the estimate omits necessary items, prepare a clear supporting package.
Include:
- The specific disputed or additional item.
- Location.
- Photographs.
- Explanation of the required work.
- Quantity and price.
- Relevant product or requirement documents.
- Updated estimate.
For concealed conditions, document findings before covering them when practical.
Avoid broad statements that “the insurer missed everything.” A location-specific explanation is easier to review.
A supplement is a request for review, not guaranteed additional payment.
12. Keep a Communication Log
Record significant calls, messages, instructions, and uploads.
Include the date, contact, subject, documents submitted, and next action.
After a call, write a factual note. Where appropriate, confirm your understanding by email.
If an adjuster changes, the log helps preserve continuity.
Use appropriate access controls for commercial records. Interior images may reveal tenant operations or sensitive equipment.
RCV Roof Claim Evidence Checklist
Claim questionUseful supporting recordsDoes RCV apply?Policy forms and roof endorsementsWhat happened?Timeline and authentic event recordsWhat is damaged?Photographs and professional findingsWhat work is needed?Supported scope and measurementsWhat does it cost?Itemized estimate and pricing supportWas urgent protection provided?Emergency scope, photos, invoicesWas permanent work performed?Completion records and final invoiceWhat was paid?Payment records when requiredIs more payment available?Policy conditions and depreciation explanationWhat was submitted?Communication log and upload confirmations
Common Mistakes
Avoid relying on the RCV label without reading roof endorsements, delaying reporting until all records are complete, submitting unidentified close-ups, or treating an estimate as proof of completed work.
Also avoid assuming full replacement, upgrade coverage, or depreciation recovery is guaranteed.
Accurate, organized evidence supports review. It does not replace the policy.
Frequently Asked Questions
Does RCV mean insurance pays for the entire roof?
No. The covered scope must be established, and deductibles, limits, exclusions, and conditions apply.
Do I need proof that the roof was repaired?
Often, additional replacement cost payment requires qualifying repair or replacement evidence. Confirm your policy’s requirements.
Will the insurer accept photographs alone?
Photographs may support findings, but costs and completion can require additional records.
Is every depreciation deduction recoverable?
No. Ask the insurer to identify recoverable amounts and conditions.
Can I wait to report until the inspection is complete?
Report promptly and provide additional documentation as it becomes available.
What if the contractor and insurer disagree?
Identify whether the issue concerns damage, scope, pricing, or coverage. Seek appropriately qualified advice for policy or legal disputes.
Build a Clear Record From Inspection to Completion
An RCV roof claim needs documentation across several stages: damage, scope, cost, protection, completed work, and any request for additional payment.
Need a roof assessment or documented construction scope for your Texas property? Contact Showtime Exteriors to discuss the roof condition and repair options.
Call [817-400-ROOF (7663) (line 8174007663)](tel:8174007663) or visit ShowtimeExteriors.com.